 Remediate RenovationBay Area and Dallas–Fort Worth · 24/7, a person answers
(281) 671-7777
Don't Wait—Call Remediate.
Insurance restoration with nothing real left out of the estimate
Remediate Renovation is the repair contractor on insurance-funded water, fire and mold jobs in the San Francisco Bay Area and Dallas–Fort Worth, and a person answers 24/7. We're an approved vendor with many insurance companies. For the covered repair you pay only your deductible; your insurer pays us the rest directly. Before a single line item is written, every affected surface is measured, photographed and moisture-mapped, so the estimate your adjuster sees shows all of the damage we will repair.
- Insured
- Approved vendor with many insurance companies
- A person answers, 24/7
- Free consultation and quote
Who does what
We're your repair contractor, not your adjuster
What we do
We find the damage, document it, write an itemized estimate for our repair and do the work: drying, removal and the rebuild with new material.
What stays between you and your insurer
Your claim, your coverage and your settlement. We don't negotiate claims or interpret policies. A licensed public adjuster or an attorney does that, if you choose to hire one.
What you get
An estimate your adjuster can check line by line, with the photos, readings and measurements behind every line.
Why it matters
Damage that is never measured is never on anyone's list. Water runs under floors and behind walls, and smoke reaches rooms the fire never touched.
How it goes
How an insurance-funded repair works, step by step
Call and stop the damage
Water out, wet material removed, the house made safe. Your policy asks you to prevent further damage, and this is that step.
Document everything
Photos of every affected surface, moisture readings written down, every room measured.
Itemized estimate
Our estimate for the repair, written in Xactimate, shared with you and with your adjuster.
Questions about the scope
When your adjuster asks about our estimate, photos or readings, we answer as your repair contractor.
Hidden damage, documented
If opening a wall shows more damage, we photograph and measure it and send an updated estimate for that work.
Repair and hand back
The rebuild with new material, and the paperwork you need to close out the job.
The first consultation and quote are free.
Reading the estimate
What's in our estimate, and how to read it
Already known to your insurer
We're an approved vendor with many insurance companies, so our estimates and paperwork arrive in the format they work with.
Xactimate
The estimating software many insurers and contractors use, with price lists for each region, updated over time. The price list used is named on the estimate.
Scope, then price
Most differences between two estimates are about scope: which rooms, how many square feet, which steps. Check the list before the totals.
Every line has proof
Each line item ties to a measurement, a reading or a photo in the file.
Overhead and profit
A line some estimates carry when a general contractor runs several trades on one job. Whether it is paid depends on your policy and your insurer.
Code items
When a repair has to meet today's building code, that cost may depend on your policy's ordinance or law coverage. Ask your insurer.
Upgrades, priced apart
Anything you want beyond putting the house back, like a better floor, is priced on its own, so the repair estimate stays clean.
Two states, a few differences
California and Texas handle a few things differently
California
The state's fair claims rules (10 CCR 2695.9) say an insurer may not depreciate repair labor, and that replaced items should give a reasonably uniform look. After the first payment you generally have at least 12 months to collect the full replacement cost, and 36 months after a declared state of emergency (Insurance Code 2051.5).
Texas
The insurer has set deadlines to acknowledge, decide and pay a claim (Insurance Code chapter 542). Whether matching materials are paid depends on your policy. Home policies issued or renewed from January 1, 2026 include an appraisal process for disputes over the amount.
Where to check
Rules change, and your policy decides most of it. The California Department of Insurance and the Texas Department of Insurance explain your rights in plain words.
What you pay
Your deductible, payment and your mortgage company
Your deductible, and only that
Your deductible is the one part of the covered repair you pay. We never waive, cover or rebate it. In Texas the law forbids it, and our contracts there carry the notice it requires.
How we're paid
For the covered repair, you pay only your deductible. Your insurer pays us the rest directly, so you don't pay us up front.
If a lender is on the check
Mortgage companies often hold larger insurance payments and release them in stages. We give them the signed estimate and the paperwork they ask for, so the stages keep moving.
Your options
If you disagree with your settlement
Ask for it in writing
Ask your insurer for their estimate, so you can compare it with ours line by line.
A licensed public adjuster or an attorney
They can negotiate the claim for you. We can't, and we don't.
Appraisal
Many policies have an appraisal clause for disputes over the amount. Your policy says how it works.
The state
You can file a complaint with the California Department of Insurance or the Texas Department of Insurance.
Whoever you choose, we can give them our photos, readings and estimate.
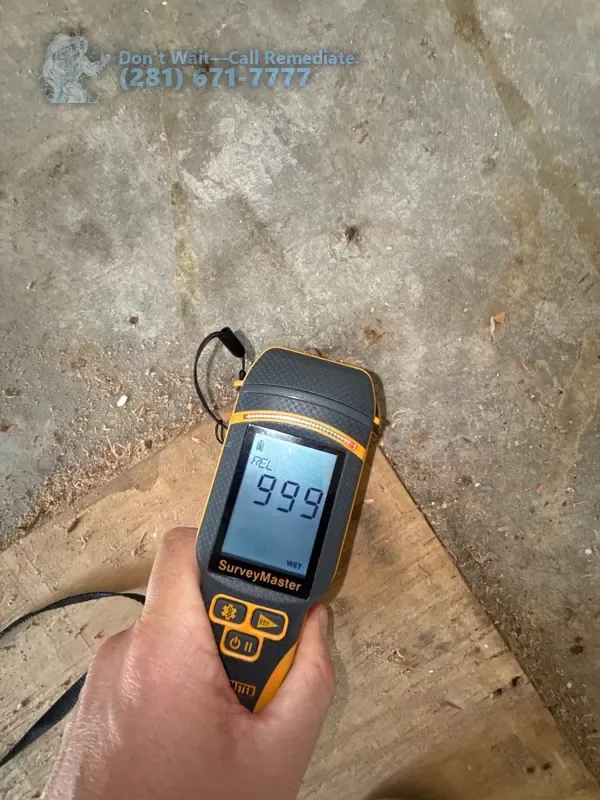
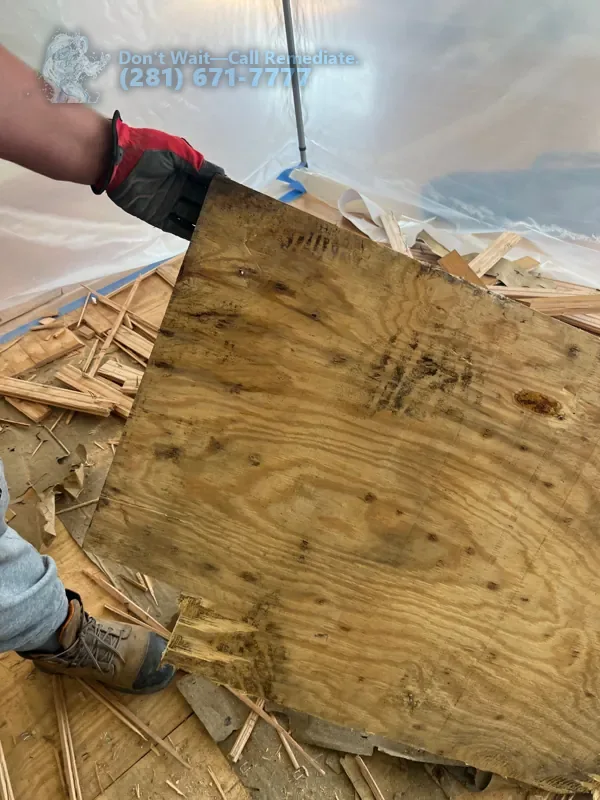
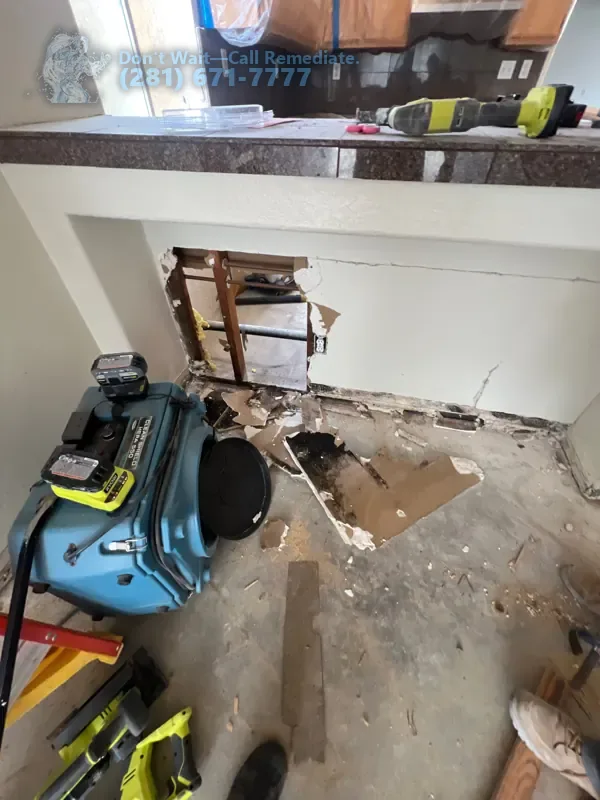
A real job in Fremont, 2026
One water job, documented from the first reading
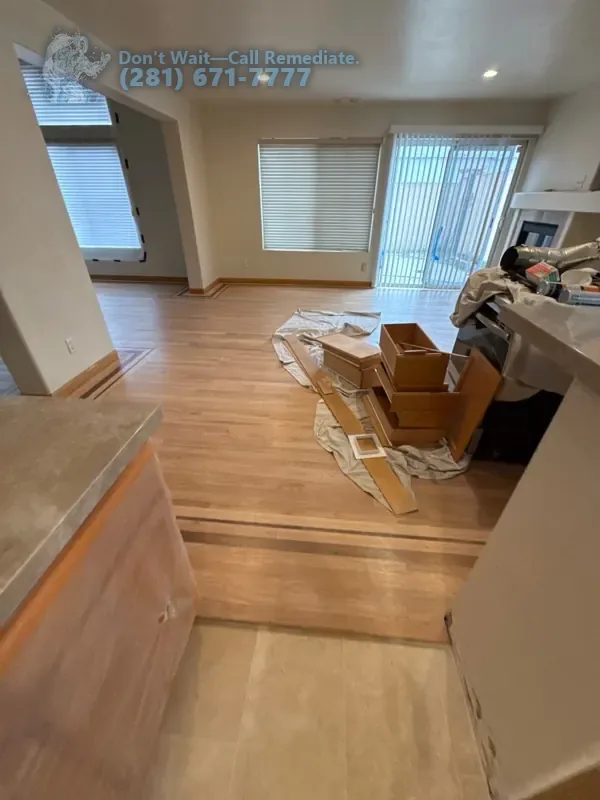
Water under a hardwood floor next to a kitchen. The first reading, the tear-out, the drying and the new floor, all on file.
All 4 photos, one by one
The repairs this applies to
Where we do insurance-funded repairs
In the San Francisco Bay Area and in Dallas–Fort Worth. See the cities we have worked in.
Questions
What people ask about repairs paid by insurance
Why is the adjuster's estimate different from yours?
Usually because of scope, not price. Many insurers and contractors use the same estimating software, Xactimate, with the same regional price list, so the difference is mostly in what is on the list: which rooms, how much material, which steps. Our estimate shows every line item with its measurement and photos, so the difference can be checked line by line.
What happens if you find more damage once the walls are open?
We stop that part of the work, photograph it, take readings and measure it, and send your adjuster an updated estimate for that work before it goes ahead. Hidden damage is common with water: it runs under floors and behind walls where nobody can see it on the first day.
Can you cover or waive my deductible?
No. Your deductible is yours to pay under your policy. In Texas, waiving, absorbing or rebating a deductible is a crime for a contractor (Business and Commerce Code 27.02), and we don't do it in California either.
Should I hire a public adjuster?
That is your choice. A licensed public adjuster or an attorney is the person who negotiates a claim on your behalf. We are the repair contractor, not an adjuster, so we don't negotiate your settlement. You can check an adjuster's license with the California Department of Insurance or the Texas Department of Insurance.
Remediate Renovation is a restoration and repair contractor, not a licensed public adjuster or a law firm. We don't negotiate claims or interpret insurance policies.
Don't Wait—Call Remediate.
Tell us what happened and who insures the house
What got damaged, when it happened, and whether you have opened a claim yet. A person answers, day or night.
Call (281) 671-7777